
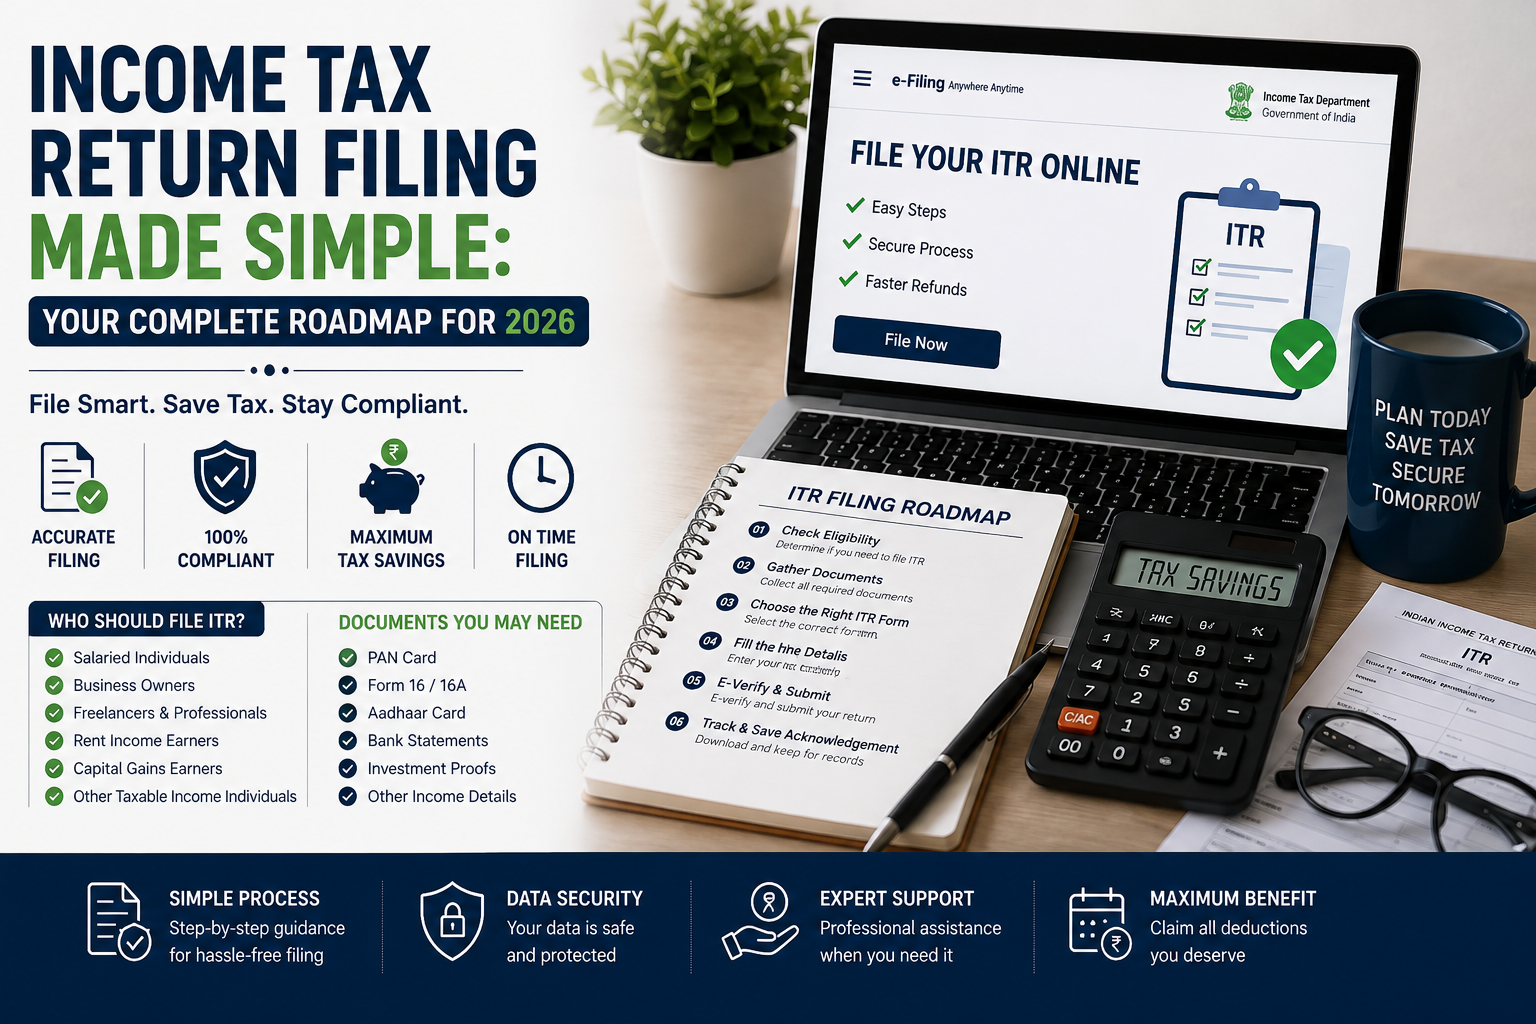
Every year, as the tax season approaches, lakhs of taxpayers across India start searching for one thing — a reliable ITR filing guide 2026 that actually makes sense. Between confusing forms, changing deadlines, and portal glitches, filing your income tax return can feel more stressful than it needs to be. This guide breaks it all down in plain language, so whether you’re a salaried employee, a freelancer, or a small business owner, you’ll know exactly what to do and when.
Why This ITR Filing Guide 2026 Matters
For Assessment Year 2026-27 (income earned during FY 2025-26), the return will still be filed under the old Income-tax Act, 1961, even though the new Income Tax Act, 2025 has come into force from 1 April 2026. This means the process, forms, and rules you’re familiar with largely remain the same for this filing cycle — the new Act only becomes relevant for income earned from April 2026 onwards, which will be filed next year. Keeping this distinction in mind is the first step of any solid ITR filing guide 2026 you follow.
Key Due Dates You Should Not Miss
Timelines are the backbone of income tax compliance, and missing them can cost you money and peace of mind. For FY 2025-26:
- 31 July 2026 – Due date for salaried individuals and taxpayers filing ITR-1 and ITR-2 without audit requirements.
- 31 August 2026 – Applicable to ITR-3 and ITR-4 filers not subject to tax audit.
- 31 October 2026 – For taxpayers whose accounts require a tax audit.
- 30 November 2026 – For taxpayers covered under transfer pricing provisions.
- 31 December 2026 – Last date to file a belated return, though with applicable late fees and interest.
- 31 March 2027 – Deadline for filing a revised return correcting any earlier errors.
Planning your filing around these dates instead of rushing at the last minute helps you avoid portal congestion, reduces filing errors, and speeds up refund processing.
Choosing the Right ITR Form
One of the most common mistakes taxpayers make is selecting the wrong form. Here’s a quick breakdown:
- ITR-1 (Sahaj): Best suited for resident individuals with salary income, one house property, and other simple sources of income within prescribed limits.
- ITR-2: For individuals and HUFs who don’t have business income but earn from capital gains, multiple properties, or foreign assets.
- ITR-3: For individuals and HUFs earning income from business or profession.
- ITR-4 (Sugam): For those opting for the presumptive taxation scheme under sections 44AD, 44ADA, or 44AE.
Choosing incorrectly can lead to your return being treated as defective, so it’s worth double-checking your income sources before you begin.
Documents to Keep Ready
Before you sit down to file, gather these essentials:
- Form 16 from your employer
- Form 26AS and Annual Information Statement (AIS)
- Bank account statements and interest certificates
- Capital gains statements, if applicable
- Proof of tax-saving investments and deductions
- Aadhaar and PAN details
Cross-checking your income and TDS details against Form 26AS and AIS before submission is one of the most important steps in any careful ITR filing process, as mismatches are a common reason returns get flagged for scrutiny.
Step-by-Step Filing Process
- Log in to the income tax e-filing portal using your PAN as the user ID.
- Select the assessment year — for this cycle, that’s AY 2026-27.
- Choose the correct ITR form based on your income profile.
- Pre-fill your data using the portal’s auto-fetch option and verify it against your documents.
- Enter deductions and exemptions under the applicable sections.
- Compute your tax liability and pay any balance tax due before submission.
- Submit and e-verify your return using Aadhaar OTP, net banking, or a digital signature.
E-verification is a step many people forget, but your return isn’t considered complete until it’s verified, usually within 30 days of filing.
Common Mistakes to Avoid
Even careful taxpayers slip up sometimes. Watch out for:
- Filing under the wrong ITR form
- Ignoring mismatches between AIS/Form 26AS and your actual income
- Forgetting to report income from savings account interest or fixed deposits
- Missing out on eligible deductions due to poor documentation
- Delaying e-verification after submission
Avoiding these small errors can save you from receiving unnecessary notices later.
Benefits of Filing Early
Filing well ahead of the deadline isn’t just about ticking a compliance box. Early filers typically enjoy faster refund processing, fewer technical hiccups on the portal, and more time to fix errors if something looks off. It also strengthens your financial credibility, which matters when applying for loans, credit cards, or visas.
Final Thoughts
Tax rules and deadlines shift a little every year, so staying updated is the smartest habit you can build as a taxpayer. This ITR filing guide 2026 is designed to help you plan ahead, choose the right form, and file with confidence rather than last-minute panic. If your income situation involves multiple sources, business income, or capital gains, it’s often worth consulting a qualified professional to make sure nothing is missed and your return stays fully compliant.
Frequently Asked Questions
1. What is the last date for ITR filing for AY 2026-27? For most salaried individuals and non-audit taxpayers, the due date is 31 July 2026. Audit cases have until 31 October 2026, and transfer pricing cases until 30 November 2026.
2. Can I file my ITR after the due date? Yes, you can file a belated return until 31 December 2026, but it will attract late fees under Section 234F and interest under Section 234A.
3. Which ITR form should I use if I only have salary income? If you’re a resident individual with salary income, one house property, and no capital gains beyond permitted limits, ITR-1 (Sahaj) is generally the right choice.
4. Is e-verification necessary after submitting my return? Yes. Your ITR filing is treated as incomplete until it is e-verified, usually within 30 days of submission, through Aadhaar OTP, net banking, or a digital signature.
5. What happens if I don’t file my ITR at all? Not filing can lead to penalties, interest on unpaid tax, loss of the ability to carry forward certain losses, and possible scrutiny notices from the Income Tax Department.